why Australia and New Zealand are safe from 'bank run' contagion
- Written by: John Hawkins, Senior Lecturer, Canberra School of Politics, Economics and Society, University of Canberra
There has been a lot of talk about the risk of financial contagion following the collapse of California’s Silicon Valley Bank[1]. Perhaps too much talk.
While the frequency of bank runs[2] in the past shows the power of emotions to move markets, there’s little reason to panic.
We’re not looking at anything like the circumstances that precipitated the global financial crisis of 2008. If you’ve got your savings in any bank or credit union in Australia or New Zealand, the greatest fear is fear itself.
Just two other US banks, the New York-based Signature Bank[3] and First Republic[4] in San Francisco, have been caught up in the trouble. Internationally, the only casualty is Credit Suisse in Switzerland, whose customers have been saved by loans offered from Switzerland’s central bank and takeover by Switzerland’s largest bank, UBS[5].
It is likely that until a few weeks ago you’d never heard of Silicon Valley Bank (or Signature or First Republic). But Credit Suisse, founded in 1856, is known around the world. It was regarded as one of 30 systemically important global banks[6].
What does its troubles have to do with Silicon Valley Bank? Not much, except that fear is contagious, and the bank already had problems that made it extra susceptible to panic.
Interest rates and bond debts
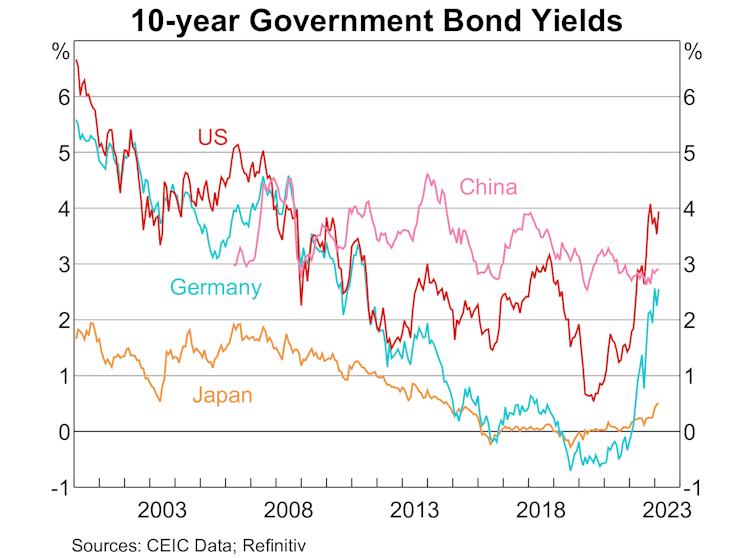
Apart from fear, the one common factor in these bank failures is the impact of higher interest rates on government bonds.
Bonds are a form of debt. Governments issue them to raise money in excess of their tax revenue. Bond buyers are paid regular fixed interest (known as a “coupon”) until the bond matures, when the issuer repays what the original buyer paid for the bond.
Banks like bonds, particularly in uncertain times. Even though they pay less interest than on other forms of debt, there’s an extremely low risk of default. Governments rarely go broke. They can always raise funds through taxation, or issuing more bonds, to meet their obligations.
Read more: We've just sold $15 billion 31-year bonds. What's a bond?[7]
In the early months of COVID, as central banks slashed interest rates as much as possible to sustain economic activity, the already low rate of interest that governments paid on bonds dropped further. In some cases this meant bond yields were even negative[8]. But they were still attractive to banks because of the low default risk compared to, say, lending money to companies facing tough times.
But the outcome of a classic “bank run” – with fear spreading through an interconnected financial system – was prevented by the US Federal Reserve stepping in to guarantee deposits.
What happened with Credit Suisse
So what has this to do with Credit Suisse? Like Silicon Valley Bank, which had poor risk controls[13], it too had specific problems indicative of poor management.
It has been implicated in providing banking services to corrupt and criminal clients[14]. In June 2022 it was convicted in Switzerland’s Federal Criminal Court for failing to prevent money-laundering by cocaine trafficker[15].
In short, Credit Suisse was a disaster waiting for a catalyst. The collapse of Silicon Valley Bank, and the talk of a global banking crisis, was enough to send already jittery customers to the exit. Credit Suisse’s largest shareholder, Saudi National Bank[16], then bluntly and publicly refused to contribute more capital.
Read more: The European Central Bank seems to have got away with raising interest rates in the middle of a banking crisis – here's why[17]
Stronger in Australia and New Zealand
In my view, the chances of any bank in Australia and New Zealand following this trajectory is effectively zero.
There’s a lot of crossover between the two countries’ financial sectors and the principal banking regulators, the Australian Prudential Regulation Authority and the Reserve Bank of New Zealand. To prevent bank runs developing, the RBNZ and APRA set minimum levels of liquid assets that can be quickly converted to cash to cover withdrawals.
It is almost a century[18] since any depositor in an Australian bank lost even a portion of their money.
This not to say there haven’t been crises.[19] For example, in 1979 the Bank of Adelaide faced collapse[20]. The RBA organised massive loans from other banks. It was then taken over by ANZ Bank. Depositors kept their savings.
In 1990 the troubled State Bank of Victoria was taken over by the Commonwealth Bank of Australia[21] (then still owned by the Commonwealth government). Again, depositors didn’t lose.
Read more: Worst bank turmoil since 2008 means Federal Reserve is damned if it does and damned if it doesn't in decision over interest rates[22]
In the very unlikely event a bank did fail, Australian depositors are also protected by a federal government deposit insurance scheme called the Financial Claims Scheme[23]. This was set up during the global financial crisis to protect customers of banks, credit unions, building societies and general insurers. It guarantees that every depositor with up to $250,000 will get their money.
The NZ government has a similar scheme[24] in the works, with legislation expected to become law later in 2023.
References
- ^ Silicon Valley Bank (theconversation.com)
- ^ bank runs (theconversation.com)
- ^ Signature Bank (theconversation.com)
- ^ First Republic (www.ft.com)
- ^ UBS (www.ft.com)
- ^ 30 systemically important global banks (www.fsb.org)
- ^ We've just sold $15 billion 31-year bonds. What's a bond? (theconversation.com)
- ^ were even negative (theconversation.com)
- ^ Reserve Bank of Australia (www.rba.gov.au)
- ^ 1.5% in November 2021 (ycharts.com)
- ^ value of existing bonds (www.rba.gov.au)
- ^ tripled (www.npr.org)
- ^ poor risk controls (www.ft.com)
- ^ corrupt and criminal clients (www.theguardian.com)
- ^ cocaine trafficker (www.reuters.com)
- ^ Saudi National Bank (www.cnbc.com)
- ^ The European Central Bank seems to have got away with raising interest rates in the middle of a banking crisis – here's why (theconversation.com)
- ^ almost a century (www.rba.gov.au)
- ^ haven’t been crises. (www.rba.gov.au)
- ^ Bank of Adelaide faced collapse (www.adelaide.edu.au)
- ^ taken over by the Commonwealth Bank of Australia (www.theage.com.au)
- ^ Worst bank turmoil since 2008 means Federal Reserve is damned if it does and damned if it doesn't in decision over interest rates (theconversation.com)
- ^ Financial Claims Scheme (www.apra.gov.au)
- ^ similar scheme (www.rbnz.govt.nz)
Authors: John Hawkins, Senior Lecturer, Canberra School of Politics, Economics and Society, University of Canberra