The cost-of-living crisis is hitting hard. Here are 3 ways to soften the blow
- Written by: Ama Samarasinghe, Lecturer, Financial Planning and Tax, RMIT University
As our wallets feel the strain from the cost-of-living crisis, many of us are looking for ways to soften the blow.
While everyone’s circumstances are different, and ideally you should seek help from an accredited financial adviser, there are some tried and true ways to work out where all your money is going and why.
Here are three practical tips to reduce the impact of the cost-of-living increases, and stretch every hard-earned dollar.
1. Hunt for a better loan rate
For many households, the biggest hit comes from the mortgage, so start there.
Even a modest 0.5% reduction can translate into substantial savings. Call your bank today and just ask for rate reduction. If the answer is no, consider shopping around for a different lender.
Your loyalty to your current lender might be costing you more than you realise. Banks often reserve their most attractive rates for new customers, leaving long-time customers paying higher-than-necessary interest.
Even if your bank does agree to a rate reduction, explore the market anyway. There is a range of free rate-comparison websites, or you can directly check individual bank websites.
If you find a lender offering a better rate, you might consider calling the competing bank to ask about switching your mortgage to them.
Or, you might seek assistance from a mortgage broker, who can guide you through the process of securing a better deal (just remember they often take commissions[1] from lenders).
Tread carefully and factor in any exit fees or charges from your current lender. Refinancing isn’t without risk, so a thorough cost-benefit analysis is important before making the switch.
Also consider the value of features such as offset accounts[2]. An offset account, linked to your home loan, allows you to deposit money such as your salary and savings. This money is then “offset[3]” against your home loan balance.
That means you only pay interest on the outstanding amount (the loan minus whatever salary and savings you put in the offset). This can accelerate loan repayment and reduce interest costs.
Keep in mind that offset accounts are typically only available with variable interest rates. Offset accounts work best if you have considerable savings to put into the offset account that outweigh the additional fees and charges attached to offset accounts.
2. Trim your expenses and uncover hidden savings
It’s time to become a budget detective, identifying and cutting down on non-essential costs that might be quietly draining your wallet.
Take a close look at those recurring memberships and subscriptions. How often do you actually use that gym membership or streaming service?
Many banking apps have handy spending tracking features to help you set realistic budget goals for each spending category.
According to the Australian Bureau of Statistics[4], insurance and financial services are among the top risers in living cost indexes (which measure the price change of goods and services and its effect on living expenses). So search comparison websites for better insurance premiums.
Australia’s insurance market is competitive, and you can often get discounts by bundling your insurances together (for example, having your home and contents insurance with the same company that also provides your car insurance). However, don’t shy away from exploring different insurers for potentially better value.
Don’t overlook energy costs, either. Use comparison websites like Energy Made Easy[5] (or, if you’re in Victoria, the Victorian Energy Compare[6] site) to find more cost-effective energy plans. Stay updated on rebates and concessions via the federal government’s Energy.gov.au[7] site, to ensure you’re maximising your entitlements.
Use less energy, if you can. Small adjustments can make a significant dent in your bills. And for fuel costs, find websites and applications that allow you to lock in the lowest prices in your area.
If you’re renting, ask yourself whether moving to a cheaper suburb or a cheaper home is an option.
Many people use cashback sites like Cashrewards and ShopBack to accrue cashback incentives.
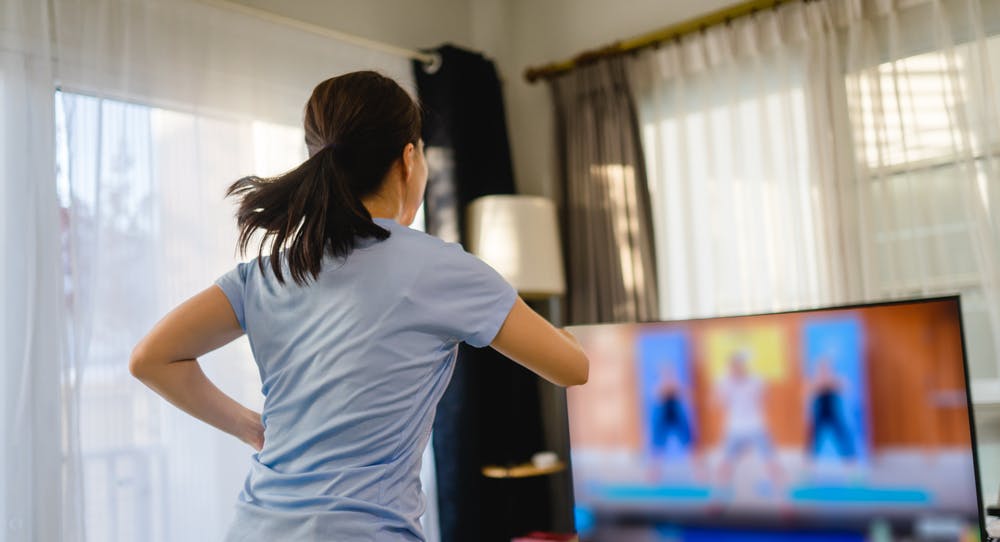 Do you get good value from your gym membership or could you save by exercising at home?
Shutterstock[8]
3. Maximise returns and tackle high-interest debts
While rising interest rates might make your mortgage climb, it also means high interest on your savings.
Consider exploring high-yield savings accounts; with current interest rates, you could potentially earn around 5.5% with a bank savings account. Many people set up recurring transfers to help them stick to savings goals, increase deposits and maximise interest earnings.
For those wrestling with high-interest debts such as credit cards or personal loans, prioritise settling outstanding balances to minimise interest payments. It can be hard to escape the long-term repercussions (such as a poor credit score[9]) of defaulting on high-interest loans[10].
And approach buy-now, pay-later services with extreme caution. They may seem tempting but the debts can quickly add up[11].
And if you need more help, contact the government’s free National Debt Helpline on 1800 007 007.
References
- ^ commissions (www.canstar.com.au)
- ^ offset accounts (moneysmart.gov.au)
- ^ offset (www.rba.gov.au)
- ^ Australian Bureau of Statistics (www.abs.gov.au)
- ^ Energy Made Easy (www.energymadeeasy.gov.au)
- ^ Victorian Energy Compare (compare.energy.vic.gov.au)
- ^ Energy.gov.au (energy.gov.au)
- ^ Shutterstock (www.shutterstock.com)
- ^ poor credit score (theconversation.com)
- ^ high-interest loans (www.sydney.edu.au)
- ^ debts can quickly add up (onlinelibrary.wiley.com)
Authors: Ama Samarasinghe, Lecturer, Financial Planning and Tax, RMIT University