With seas rising and storms surging, who will pay for New Zealand’s most vulnerable coastal properties?
- Written by: Tom Logan, Lecturer of Civil Systems Engineering, University of Canterbury
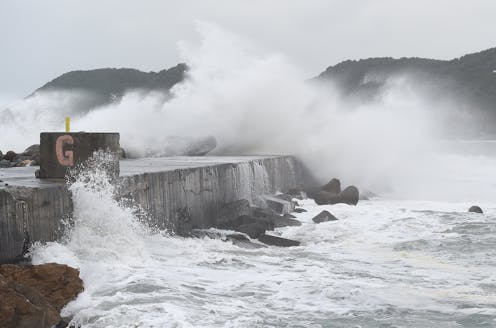
The major storm surge and coastal flooding in Wellington[1] earlier this month was another reminder that the sea is now lapping close to a lot of New Zealand’s front doors. The ominous question is: who will pay when it crosses the threshold?
But that’s not a question worrying insurance companies. They’ve made their position clear — they won’t be paying for it[2].
Insurance is based on uncertainty and is reevaluated annually. When the chance of damage rises beyond what an insurance company is prepared to bear, it withdraws.
This leaves at-risk homeowners with no insurance, either private or through the state’s Earthquake Commission[3]. In the meantime, homeowners will likely continue to pay rising premiums, possibly unaware of the tenuous nature of their coverage.
The latest research[4] tells us coastal properties will start to lose insurance cover within the next ten years, if not sooner. Technically, if your property has a 1% chance of coastal damage with today’s sea level, you’ll likely lose all private insurance once the chance rises to 5% — anticipated to be less than 25 years away[5].
That means potentially more than 30,000 residential properties – currently valued at more than NZ$17 billion – are expected to be uninsurable within the next few decades.
Furthermore, these timelines don’t account for the latest predictions[6] of polar ice sheet tipping points[7]: major sea-level rise is on its way.
Who will pay?
Domestic and international precedent suggests the central government might compensate some property owners. But there’s a significant caveat: the New Zealand government has so far followed a UK model for coastal property compensation. Called “Flood Re[8]”, this only covers UK homes built before 2009.
Minister for Climate Change James Shaw has said[9] the challenge for New Zealand lies in defining where the line falls. He also said developers of coastal properties today are doing so “with their eyes open”.
Read more: When climate change and other emergencies threaten where we live, how will we manage our retreat?[10]
This is significant and suggests the government might be positioning itself to abandon more recent coastal developments.
It’s hard to argue with such a policy. Can we expect taxpayers and the government to pay such a massive bill? More pointedly, should the government be compensating for decisions made now when local councils should at least be aware of the risks?
We’re still building by the coast
While the total rateable value of exposed residential property is approximately $17 billion, $2.6 billion of that was built after 2009, according to our analysis.
Even today, local councils are continuing to grant consent for development in these immediately exposed places. The Christchurch City Council – already with one of the highest exposures to coastal hazards – has just announced a 65-home development in New Brighton[11], an area current modelling suggests is prone to coastal flooding.
At the same time, advice from the Ministry for the Environment[12] suggests councils should be taking a risk-informed approach to land-use planning, and asks whether councils or investors can afford to write off these investments in future.
Read more: 'Managed retreat' done right can reinvent cities so they're better for everyone – and avoid harm from flooding, heat and fires[13]
This guidance is not mandatory, however, and many councils do not have the resources or expertise to take a risk-based approach. Aside from the financial threat, there are the associated physical upheavals and mental health issues facing residents.
The new Strategic Planning Act[14] (one of the three pieces of legislation replacing the old Resource Management Act) should put an end to further development in at-risk places. But this still leaves the complex financial and ethical question of what happens to existing property owners.
Simply to say these residents knew the risks when they developed and should therefore be left on their own is not an acceptable long-term, compassionate strategy. Other solutions will be needed.
Government guidance is vital
We need to be wary, however, of local communities demanding sea walls or other protections to allow them to remain. Recent research[15] indicates such structural defences can inadvertently raise long-term risk and exposure.
A more sustainable approach proposed in Hawkes Bay involves charging ratepayers $30 a year for a coastal defence or managed retreat fund[16]. Initially lauded as the country’s most sophisticated engagement process and strategy, it has since stalled due to councils being unable to agree which rates bill it should be on[17].
Another solution might be the creation of a government-managed coastal bond or insurance scheme. This would ensure the premiums paid by coastal residents stayed in the local economy to support them. Naturally, such a scheme should include conditions that limit or prevent development in risk zones.
Read more: Rising insurance costs may convince Americans that climate change risks are real[18]
Alternatively, New Zealand could adopt a framework for converting exposed property from freehold to leasehold[19], which would put time limits on occupying vulnerable properties.
The related idea of a “revolving loan program[20]” is being discussed in California. Essentially a creative buyout scheme, this would involve councils or communities buying vulnerable properties and renting them out to pay off the loan until the property is no longer safe.
Regardless, storms like those witnessed in Wellington should remind us of the need for clear guidance and support at government level. The proposed Climate Change Adaptation (or Managed Retreat) Act will hopefully provide this guidance, but this is possibly three years away[21] at best. With coastal development still happening, it’s clear we need it sooner.
In the meantime, those who are aware of the risks will be tempted to sell their vulnerable property to those who aren’t. That is no solution. New Zealand will still have vulnerable citizens in vulnerable places — regardless of whether or not they bought with their eyes open.
References
- ^ flooding in Wellington (www.stuff.co.nz)
- ^ they won’t be paying for it (www.stuff.co.nz)
- ^ Earthquake Commission (www.eqc.govt.nz)
- ^ latest research (deepsouthchallenge.co.nz)
- ^ less than 25 years away (deepsouthchallenge.co.nz)
- ^ latest predictions (www.nature.com)
- ^ tipping points (www.stockholmresilience.org)
- ^ Flood Re (www.floodre.co.uk)
- ^ James Shaw has said (www.rnz.co.nz)
- ^ When climate change and other emergencies threaten where we live, how will we manage our retreat? (theconversation.com)
- ^ 65-home development in New Brighton (www.stuff.co.nz)
- ^ advice from the Ministry for the Environment (environment.govt.nz)
- ^ 'Managed retreat' done right can reinvent cities so they're better for everyone – and avoid harm from flooding, heat and fires (theconversation.com)
- ^ Strategic Planning Act (www.stuff.co.nz)
- ^ research (www.nature.com)
- ^ managed retreat fund (science.sciencemag.org)
- ^ rates bill it should be on (www.stuff.co.nz)
- ^ Rising insurance costs may convince Americans that climate change risks are real (theconversation.com)
- ^ converting exposed property from freehold to leasehold (www.rnz.co.nz)
- ^ revolving loan program (www.npr.org)
- ^ possibly three years away (www.stuff.co.nz)