Here's another reason not to boost compulsory super: it'll ramp up debt
- Written by: James Giesecke, Professor, Centre of Policy Studies and the Impact Project, Victoria University
The government receives the long-awaited report of its retirement incomes review on Friday[1].
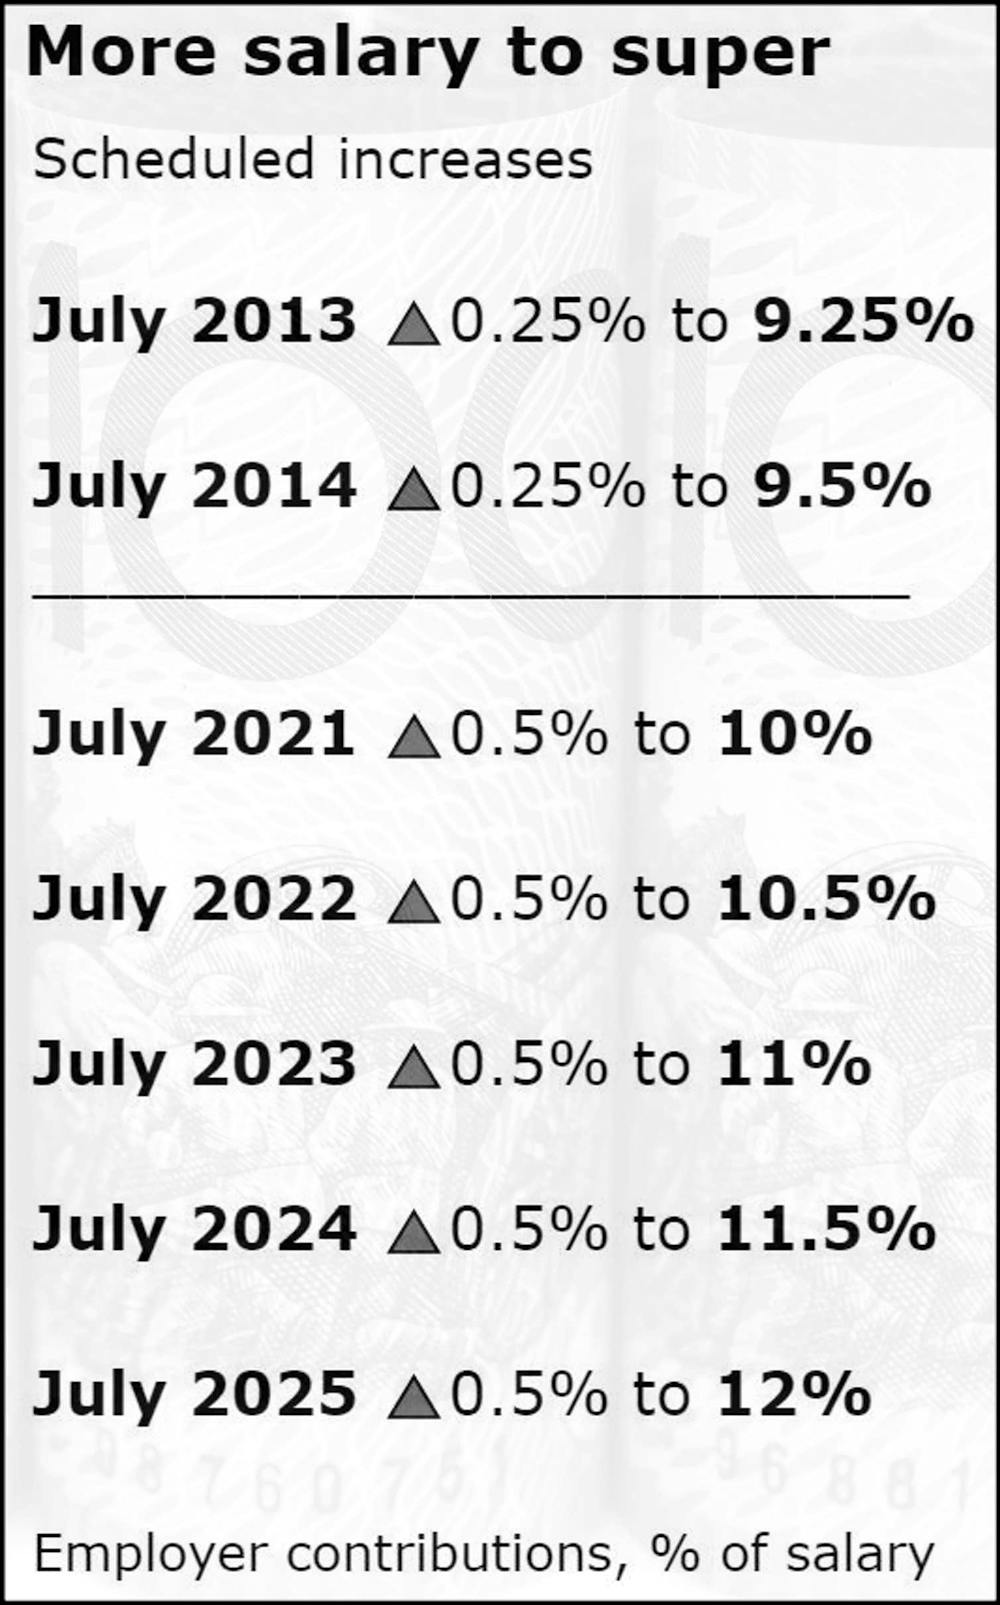 Source: Australian Tax Office[2]
Key among the questions it has been asked to examine is whether to proceed with the legislated increases in employers’ compulsory super contributions from the present 9.5% of salary to 12%, in five annual steps of 0.5% of salary, starting next July.
In a study with colleagues from Victoria University’s Centre of Policy Studies published in the Journal of Policy Modeling[3] we examined the effects of such an increase on financial stability.
We found it could have adverse impacts on two indicators of economy-wide debt: the ratio of private debt to income, and the ratio of debt to equity in housing finance.
These indicators matter[4] for stability. High debt levels tend to amplify what would otherwise be manageable economic shocks.
Ultimately paid by households
How would an increase in compulsory super contributions increase debt?
The increase will ultimately be borne by households through a matching reduction in take-home pay. How long this takes will depend on how far in advance the planned increases have been announced and on broader labour market conditions.
Regardless, the end point will be that the extra superannuation will come from employees through lower take-home pay than they would have had.
Read more:
Think superannuation comes from employers' pockets? It comes from yours[5]
Households will need to apportion the lower take-home pay than otherwise between lower spending than otherwise and lower other saving than otherwise.
How they do this will depend on how they save at the moment.
For households in which compulsory superannuation is the only or the main way in which they save, the increase in contributions will bring about extra saving. They will spend less than they would have.
For some, it’ll change the way they save
For households who are already saving more than is mandated through superannuation, the increase in contributions is more likely to lead them to cut other saving than it is to lead them to cut their spending.
For these households, total saving will be largely unchanged, but a greater proportion of it will be routed through super and a lower proportion through other types of saving.
These are the households who are likely to push up economy-wide debt.
To understand why, it is helpful to shift our focus to housing.
More borrowing, less equity
 More debt, less equity.
STEFAN POSTLES/AAP
A rise in compulsory super has little direct impact on demand for housing as shelter, whether by owner-occupiers or renters. But it does affect the way housing is financed.
In making decisions about where to allocate their saving outside of super, households show a preference for buying equity in housing.
In contrast, the super sector invests more heavily in market securities, including lending money to and buying shares in banks[6].
Shovelling more household savings into super and less into home equity will at the margin cut the amounts households are able to advance as deposits for homes and increase the amounts banks are able to lend them on top of those deposits.
The complex chain by which some savings that would have been home deposits end up financing the same homes via debt means a fair proportion of them is lost along the way[7] in fees, expenses and profit margins.
Reasons for caution
Even in normal times, these would be reasons for caution about increasing compulsory super contributions. Of course, the times aren’t normal.
COVID-19 has had a dire impact on the labour market and broader economy[8]. The recovery path is likely to be long and uncertain, with heightened risks of new economic shocks.
Before COVID-19, Australia had one of the world’s highest ratios of household debt to GDP[9]. COVID-19 will exacerbate it by pushing down GDP.
An increase in compulsory super risks pushing up household debt further, further weakening economic stability.
Read more:
5 questions about superannuation the government's new inquiry will need to ask[10]
As noted earlier, for households with low saving rates the increase in compulsory super will be accommodated by lower spending than would have been expected.
During a recession this constitutes an additional risk to recovery.
It is also worth noting that while the legislated increase in compulsory contributions will ultimately be borne by workers through lower take-home pay than otherwise, in the short-run some of it might be borne by firms.
The risk there is that by pushing up short-run hiring costs, the increase in compulsory super will delay the labour market recovery.
References
- ^ Friday (treasury.gov.au)
- ^ Source: Australian Tax Office (www.ato.gov.au)
- ^ Journal of Policy Modeling (www.sciencedirect.com)
- ^ matter (www.oecd.org)
- ^ Think superannuation comes from employers' pockets? It comes from yours (theconversation.com)
- ^ banks (www.copsmodels.com)
- ^ lost along the way (theconversation.com)
- ^ broader economy (theconversation.com)
- ^ household debt to GDP (stats.bis.org)
- ^ 5 questions about superannuation the government's new inquiry will need to ask (theconversation.com)
Authors: James Giesecke, Professor, Centre of Policy Studies and the Impact Project, Victoria University